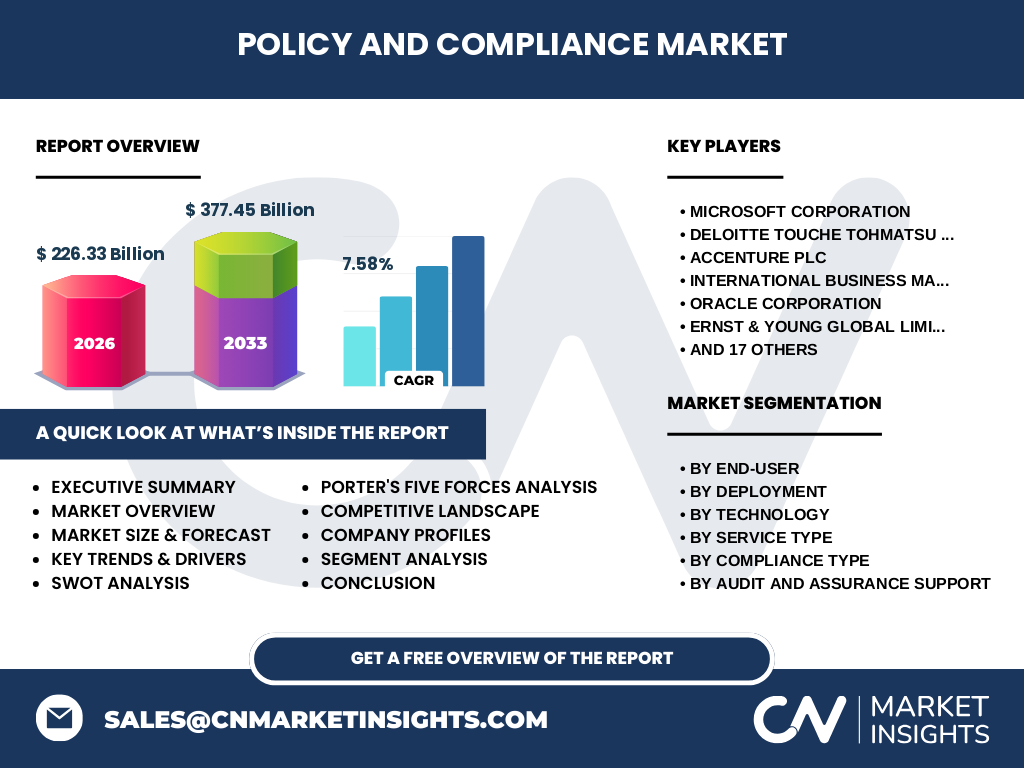
Market overview of the Policy And Compliance Market
The Policy And Compliance Market represents a critical global infrastructure valued at $226.33 Billion in 2026. It encompasses the structured management of corporate governance, regulatory adherence, and risk mitigation. Industry significance is paramount as organizations across BFSI and Healthcare navigate complex international frameworks, ensuring that internal SOPs and data privacy protocols meet the stringent mandates set by bodies like the GDPR and SOX.
Structural growth drivers, restraints, and opportunities
Primary growth is fueled by digital transformation and the proliferation of RegTech, while the market faces logistical hurdles regarding fragmented cross-border enforcement. Opportunities emerge in Compliance-As-A-Service (CaaS), which allows mid-market firms to outsource high-cost audit readiness. Restraints include the high capital expenditure required for legacy system integration and the constant evolution of localized labor laws in volatile jurisdictions, demanding agile, technology-enabled compliance solutions.
Emerging trends and growth patterns
A significant trend is the shift toward continuous controls monitoring over periodic manual reviews. Companies are moving away from siloed spreadsheets toward integrated GRC platforms. Our analysis suggests that ESG compliance is becoming a core strategic pillar, moving beyond voluntary reporting to mandatory global standards, forcing firms to adopt sophisticated automated frameworks for sustainability assurance and ethical documentation.
COVID-19 impact and recovery trajectory
The pandemic catalyzed a massive surge in cloud-based compliance adoption as distributed workforces forced organizations to digitize HR and security policies overnight. The recovery trajectory shows a pivot from reactive crisis management toward long-term resilience. Data shows that Cybersecurity compliance spending reached an inflection point, as firms sought to secure remote endpoints while adhering to heightened Data Protection mandates accelerated by the public health emergency.
Competitive benchmarking and landscape
The Policy And Compliance Market is highly concentrated, led by industry titans like Microsoft, SAP, and IBM, alongside audit powerhouses Deloitte, EY, and KPMG. Strategic dynamics favor firms offering end-to-end RegTech software. Smaller, specialized innovators like Sprinto and OneTrust compete by offering hyper-niche, automated compliance solutions that provide faster time-to-value for mid-tier enterprises compared to larger, more cumbersome legacy consulting implementations.
Executive summary of findings
The industry is poised for substantial expansion, with a projected market value of $377.45 Billion by 2033 at a CAGR of 7.58%. This trajectory reflects the escalating necessity for automated regulatory-compliance and risk-based audits. The fusion of AI-driven analytics with traditional consulting service models defines the current competitive frontier, rewarding players that bridge the gap between technical monitoring and strategic advisory.
Market forecast 2027 to 2033
Projections indicate the Policy And Compliance Market will reach $377.45 Billion by 2033. This growth, occurring at a 7.58% CAGR, is driven by the hardening of global cybersecurity laws and the increasing complexity of tax and financial compliance. We expect a shift in budget allocation toward managed services as organizations seek to mitigate rising administrative burdens via third-party expert oversight.
Segmentation analysis by end-user and deployment
Market segmentation spans critical sectors, with BFSI, Healthcare, and IT & Telecom commanding the highest spend. Deployment models vary, ranging from high-touch Consulting to automated Technology-Enabled Compliance. This bifurcation allows firms to choose between capital-heavy software investments—like ServiceNow's GRC suite—and flexible, service-based engagements that are essential for small-to-medium enterprises requiring expert Internal Audit Support without significant internal headcount.
Regional performance and geographic distribution
North America retains the largest share due to stringent enforcement by regulatory bodies like the SEC, while the APAC region exhibits the fastest growth. European markets remain highly focused on data privacy and GDPR. Our research suggests that regional growth is deeply tied to the presence of major financial hubs, such as London, Singapore, and New York, where compliance pressure is consistently highest.
In-depth regional review
North America remains the leader in regulatory-compliance software adoption, driven by complex corporate disclosure requirements. Conversely, EMEA dominates the data protection and ESG policy documentation sector. The APAC market is characterized by a rapid transition toward statutory compliance, as emerging nations update their legal infrastructure to attract international investment, providing lucrative opportunities for local consultancy firms and global SaaS providers like VComply.
Strategic positioning of leading companies
Market leaders employ distinct strategies: Deloitte and EY emphasize deep consulting and advisory expertise to handle complex forensic audits. Meanwhile, Oracle and SAP leverage their existing enterprise software dominance to embed GRC platforms into global supply chains. Tech-first firms like OneTrust and MetricStream focus heavily on user-friendly dashboards for real-time monitoring, catering to businesses that require agility over legacy heavy-lifting.
Porter's Five Forces analysis
The Policy And Compliance Market exhibits high barriers to entry due to the specialized knowledge required for regulatory interpretation. Supplier power is moderate, concentrated among a few global technology giants. However, competitive rivalry is intense, with Consulting vs. RegTech models constantly clashing. Threat of substitutes is low, as compliance is mandatory, yet clients frequently swap providers to find superior automation and efficiency.
SWOT analysis of the sector
Strengths: Mandatory nature drives predictable recurring revenue. Weaknesses: High integration costs for legacy ERP systems. Opportunities: Rapid scaling of AI-driven Compliance-As-A-Service for the SME market. Threats: Rapidly shifting regulatory landscapes that may outpace current policy management platforms, creating potential gaps in risk assessment accuracy for firms failing to update their frameworks timely.
Value chain analysis and industry structure
Value flows from initial regulatory updates through compliance framework design and policy documentation, eventually reaching end-users via monitoring and reporting software. Raw materials here refer to intelligence and legal data updates. Intermediaries like Intertek provide the assurance layer, while software providers create the continuous controls monitoring infrastructure that connects audit findings to strategic corporate decision-making at the board level.
Investment insights and strategic recommendations
Investors should target high-growth SaaS compliance providers focusing on ESG and automated third-party risk assessment. Our analysis indicates that the $377.45 Billion market potential is skewed toward companies that integrate forensic audit capabilities with real-time reporting. Prioritizing investments in firms that have proprietary Regulatory Interpretation algorithms will provide a competitive edge in capturing the burgeoning middle-market compliance spend.
Conclusion and key takeaways
The Policy And Compliance Market is a fundamental engine of global corporate stability. With a market expansion reaching $377.45 Billion by 2033, the shift toward automation and managed services is irreversible. Success hinges on a firm's ability to provide scalable, tech-enabled compliance that simplifies complex global frameworks while maintaining a balance between rigorous audit readiness and operational agility.
Research methodology for the report
Our analysis is derived from triangulation of trade registry data, primary stakeholder interviews with C-suite executives, and secondary macroeconomic indicators. We cross-reference growth estimates against regional regulatory changes and compliance expenditures in the BFSI and IT sectors. This rigorous, evidence-based approach ensures that the market sizing projections represent an authoritative reflection of global trends in the Policy And Compliance Market.
Scope of the report coverage
This report covers the global Policy And Compliance Market from 2026 to 2033. It spans regulatory-compliance software, consulting services, and GRC platforms across all primary industry segments. Limitations include focusing primarily on formal commercial markets, excluding informal or localized legislative nuances that lack standardized reporting, thus providing a high-level strategic roadmap for institutional investors and multinational operational leadership.
Recent industry developments
Recent activity highlights a wave of M&A, as legacy giants like ServiceNow acquire specialized RegTech vendors to bolster their continuous controls monitoring. Meanwhile, companies like Sprinto and Usercentrics are launching automated Data Privacy and Protection suites that cater to a globalized, web-first compliance model. These moves signal a broader industry consolidation toward integrated, AI-powered compliance ecosystems that provide immediate visibility across global offices.